After several challenging years for the natural diamond industry, there are growing signs that the market may finally be reaching a period of stabilisation.
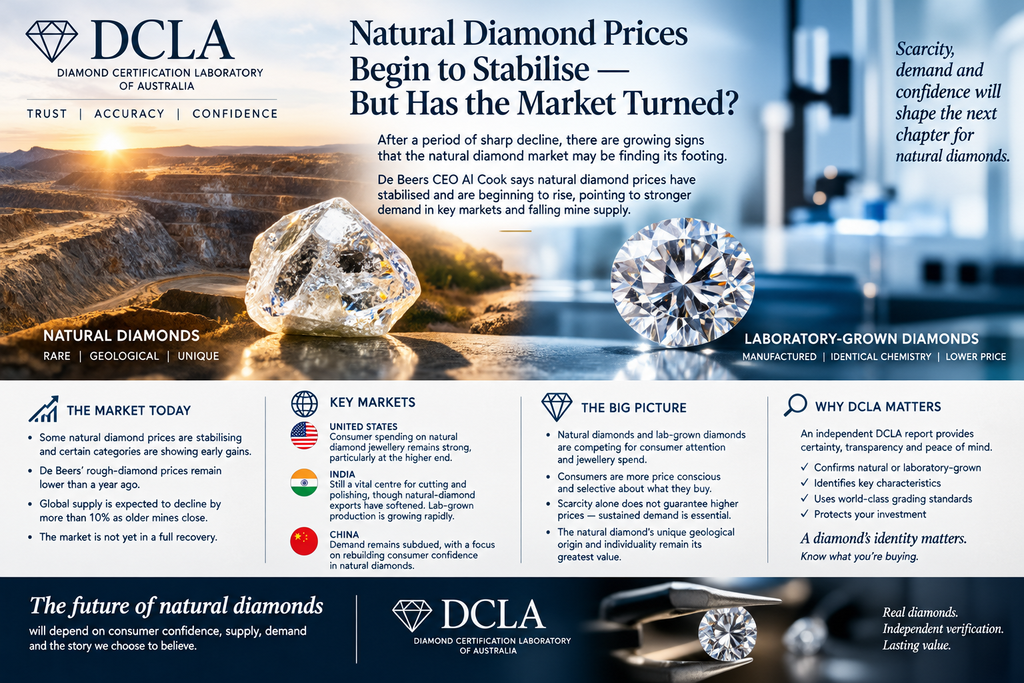
De Beers Group CEO Al Cook recently said natural diamond prices had stabilised and were beginning to rise, pointing to improving demand in key markets and declining mine supply.
Speaking in Beijing on 15 September during the signing of the Beijing Declaration on Natural Diamonds and Sustainable Development, Cook said:
“In the last few months, we’ve seen the price stabilise and begin to grow.”
Cook attributed the change to stronger consumer demand, particularly in the United States and India, combined with declining supply as some older diamond mines approach the end of their productive lives.
He said global diamond supply was currently falling by more than 10%, creating a potentially important change in the supply and demand balance.
However, the broader market remains considerably more complicated.
A Recovery, Or Simply Stabilisation?
De Beers’ own financial results demonstrate why the industry should be cautious about describing current conditions as a full recovery.
During the first half of 2026, De Beers’ average realised rough-diamond price fell significantly compared with the previous year, while its rough-diamond price index also declined.
This means that while some areas of the market are showing signs of improvement, the industry has not yet returned to the pricing environment seen during the post-pandemic period.
There is an important distinction between prices stopping their decline and prices entering a sustained recovery.
Recent market data has shown improvement in some polished natural-diamond categories, particularly certain smaller stones and selected higher-quality goods. Larger and higher-value diamonds have also demonstrated greater resilience.
But other categories remain under pressure.
The United States Remains Important
The United States continues to be one of the most important markets for natural diamonds.
Consumer spending on natural diamond jewellery has remained relatively resilient, particularly at the higher end of the market. This suggests that consumers continue to place value on the rarity, provenance and enduring appeal of natural diamonds.
The market is nevertheless becoming increasingly divided.
Consumers purchasing higher-value jewellery appear more willing to spend, while lower-priced categories face much greater competition from laboratory-grown diamonds and changing consumer expectations.
India: A Critical Part of the Global Diamond Industry
India remains central to the international diamond trade, particularly because of its enormous cutting and polishing industry.
However, natural-diamond exports have faced pressure, reflecting weaker international demand, inventory adjustments and changing market conditions.
At the same time, laboratory-grown diamond production has expanded rapidly.
This is an important development because India is now producing enormous quantities of laboratory-grown diamonds alongside its traditional natural-diamond manufacturing industry.
The two products occupy different positions in the market, but they increasingly compete for consumer attention and jewellery expenditure.
China Remains a Key Challenge
China is another critical part of the global diamond market, but demand has remained subdued.
De Beers has acknowledged the importance of rebuilding consumer confidence in natural diamonds in China, including communicating the rarity and long-term significance of natural diamonds to a new generation of consumers.
The Beijing Declaration reflects the industry’s attempt to strengthen relationships between diamond-producing countries in Africa and the Chinese jewellery market.
For the natural diamond industry, China represents both a major opportunity and a significant challenge.
Natural Diamonds and Laboratory-Grown Diamonds
The growth of laboratory-grown diamonds has fundamentally changed the jewellery market.
Laboratory-grown diamonds are diamonds with essentially the same chemical composition and crystal structure as natural diamonds, but they are produced through technological processes rather than geological formation.
Their ability to be manufactured in large quantities has resulted in substantial price reductions.
This creates a very different proposition for consumers.
A laboratory-grown diamond can provide the physical characteristics of a diamond at a significantly lower price, while a natural diamond represents a finite geological resource formed over billions of years.
For the jewellery industry, the challenge is therefore not simply about price.
It is about what consumers believe they are purchasing and why they value it.
Scarcity Alone Does Not Guarantee Higher Prices
One of the most interesting arguments being made by the natural diamond industry is that declining mine production could eventually create a tighter supply-demand balance.
That is certainly possible.
But scarcity by itself does not guarantee higher prices.
For any scarce product to appreciate, there must also be sustained demand and a willingness among consumers to pay for its scarcity.
This is why the industry’s efforts to communicate the differences between natural and laboratory-grown diamonds are becoming increasingly important.
Natural diamonds have a unique geological history. Every natural diamond is the product of extraordinary geological conditions over immense periods of time. That rarity is fundamentally different from a product that can be manufactured repeatedly in a laboratory.
What Is Happening to the Jewellery Market?
The wider jewellery market is also changing.
Consumers around the world are becoming more price conscious, particularly as the cost of living and precious-metal prices remain elevated.
Gold provides an interesting comparison. Although jewellery demand measured by weight has fallen in some major markets, the value of jewellery purchases has remained much stronger because of significantly higher gold prices.
The same trend can be seen within diamonds.
Consumers are not necessarily abandoning fine jewellery. Instead, they are becoming more selective about what they purchase, where they purchase it and what they believe gives a piece lasting value.
This is creating a more polarised market, with strong interest in exceptional natural diamonds and luxury jewellery at one end, and highly price-sensitive consumers choosing laboratory-grown diamonds at the other.
What Does This Mean for Natural Diamonds?
The latest evidence suggests that the natural diamond industry may be moving away from the severe price declines experienced over recent years.
There are encouraging signs in certain categories and markets, and declining mine production could eventually become an important factor.
However, it would be premature to describe the entire natural diamond market as being in a confirmed recovery.
The industry is still dealing with excess inventory, weaker demand in some major markets, changing consumer behaviour and intense competition from laboratory-grown diamonds.
For DCLA, one point remains particularly important:
A diamond’s identity matters.
Whether a stone is natural or laboratory-grown should be clearly disclosed and independently verified. Consumers should understand exactly what they are purchasing and the characteristics that distinguish one from the other.
The future of the natural diamond market may ultimately depend not simply on declining supply, but on whether consumers continue to value the extraordinary rarity, geological origin and individuality of a natural diamond.
For now, the evidence points to stabilisation and early signs of improvement rather than a confirmed return to the strong diamond market of previous years.
The next stage will depend on consumer confidence, global economic conditions, mine supply, jewellery demand and how the industry communicates the fundamental difference between a diamond created by nature over billions of years and one created by modern technology.
Comments are closed